Audit: Discrepancies found between Buruni Council’s 2024 approved and revised budget figures and official financial records
6 ނޮވެމްބަރު 2026 | ހުކުރު 18:57An audit report has revealed discrepancies between the financial statements and actual accounts of the Th. Buruni Council due to errors made while recording data in the "Viya" module. Consequently, the Auditor General’s Office has instructed the council to ensure the accuracy of its financial statements by correctly entering budget figures into the system.
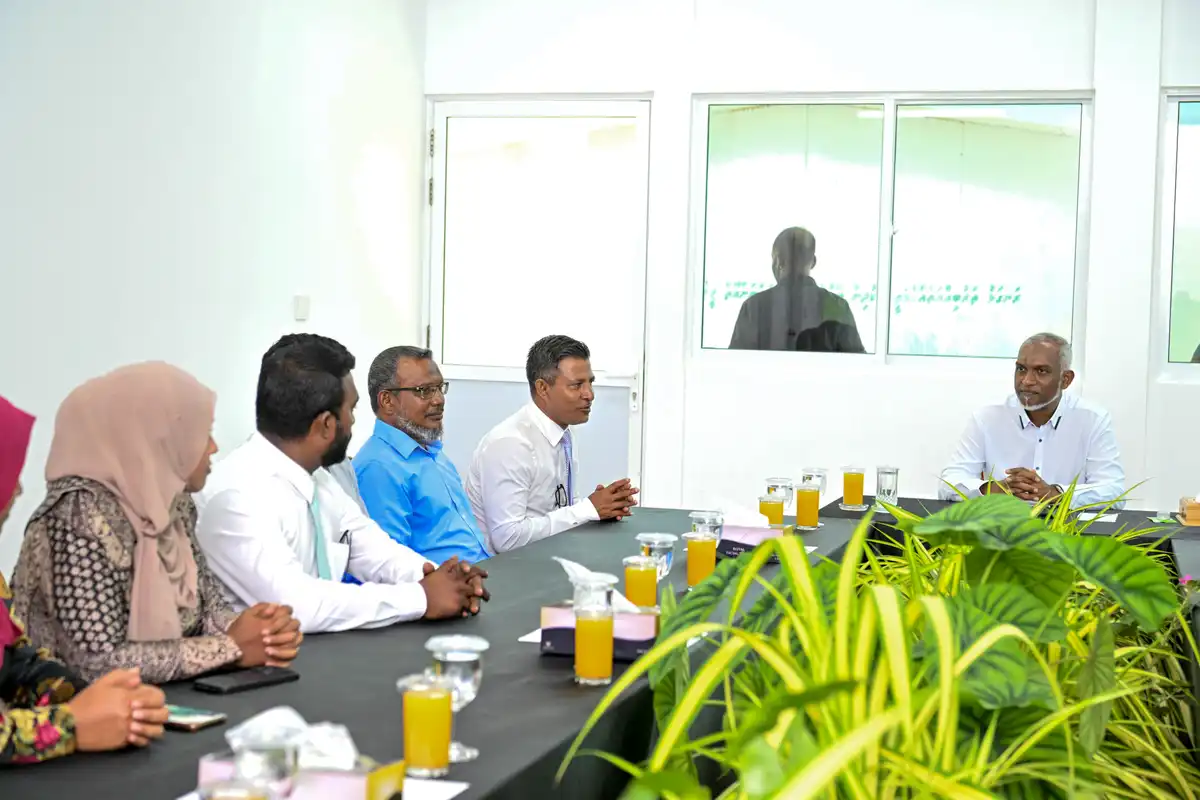
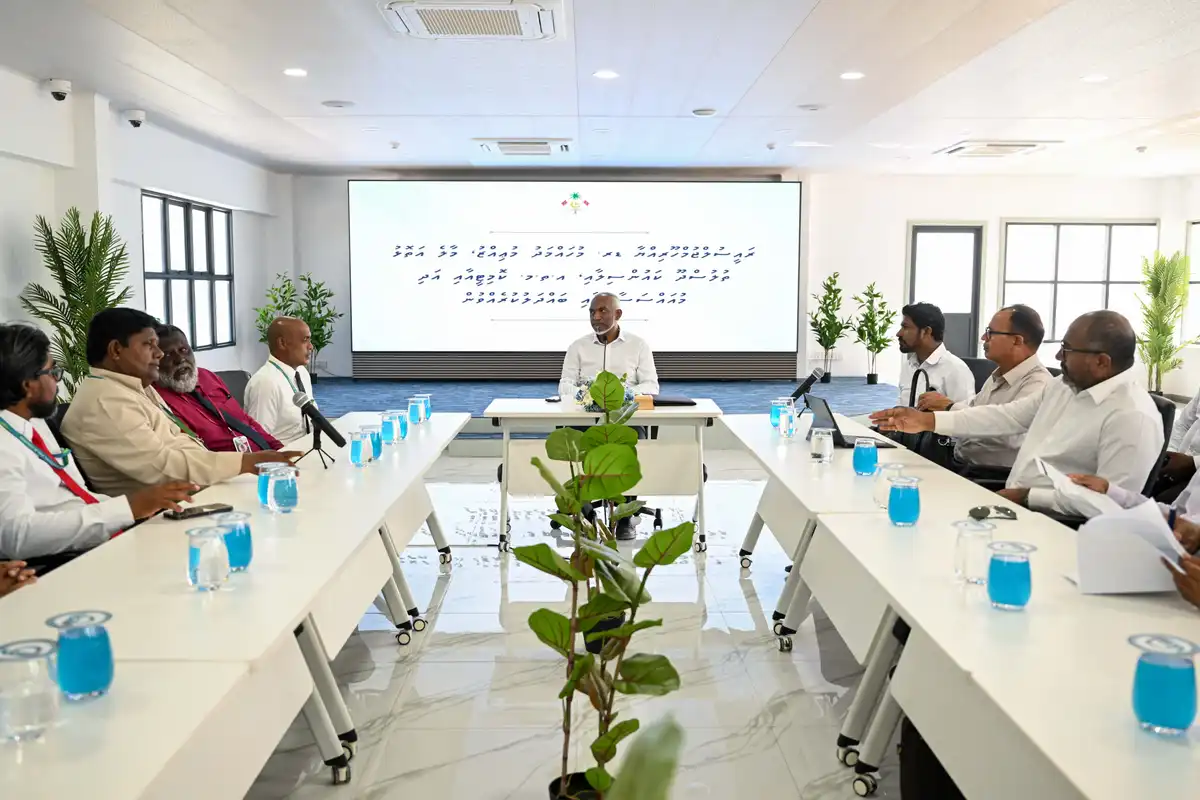
President meets with the Burunee Island Council and the Women's Development Committee (WDC). | President's Office
The Auditor General’s Office has stated that the revenue and expenditure figures in the Th. Buruni Council’s 2024 approved budget and the revised budget statement do not reconcile with the council’s financial records.
The 2024 compliance audit report for the Thaa Atoll Buruni Council, released by the Auditor General’s Office, highlighted discrepancies between the revised budget figures stated in the council's financial statements and the revised budget figures calculated by auditors based on the council's official records.
The Audit Office stated that the discrepancy arose because figures were entered into the "Viya" module as a supplementary budget in addition to the original budget approved by the Council, with the financial statements subsequently reflecting these figures as a revised budget. However, the Audit Office noted that the amounts recorded as a supplementary budget in the "Viya" module had not been approved by the Council. The office further clarified that these figures were included due to an accounting error in the record-keeping process.
Issuing recommendations for corrective action, the Auditor General’s Office instructed the council to ensure that budget figures are accurately recorded in the administrative accounting system. The office specifically directed the council to verify that the figures entered into the 'Viya' module—for both the approved and supplementary budgets—strictly reflect the amounts officially passed by the council. Furthermore, the council was instructed to ensure that all figures included in financial statements are authentic and consistent with the institution's official accounting records.