Audit: Vilufushi Council Missed Financial Reporting Deadline, Records Don’t Reconcile
21 ސެޕްޓެމްބަރު 2026 | ހޯމަ 09:01An audit of the Th. Vilufushi Council has revealed significant discrepancies exceeding one million Rufiyaa between their financial statements and "Viya" module records, following the council's failure to submit reports within the statutory deadline. Due to these substantial inconsistencies in income and expenditure figures, the Auditor General has urged the council to strengthen its financial management systems and ensure the accuracy and integrity of its future financial reporting.
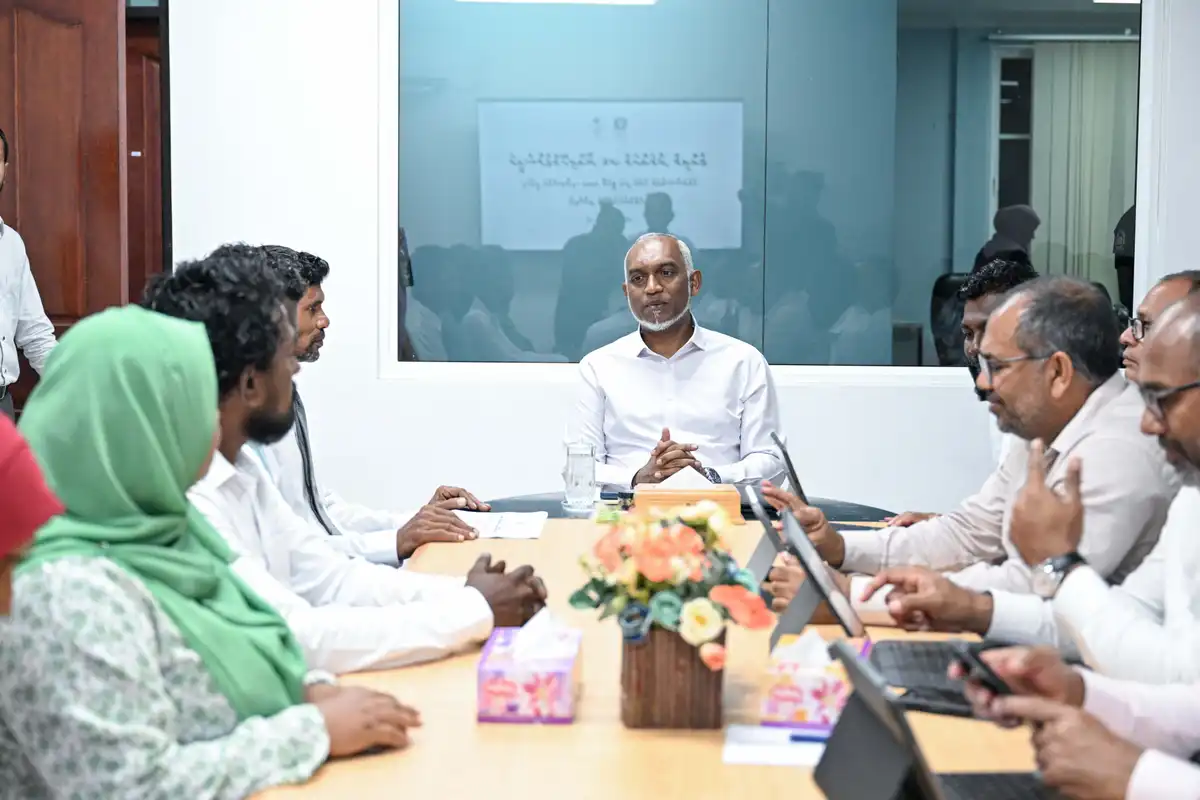
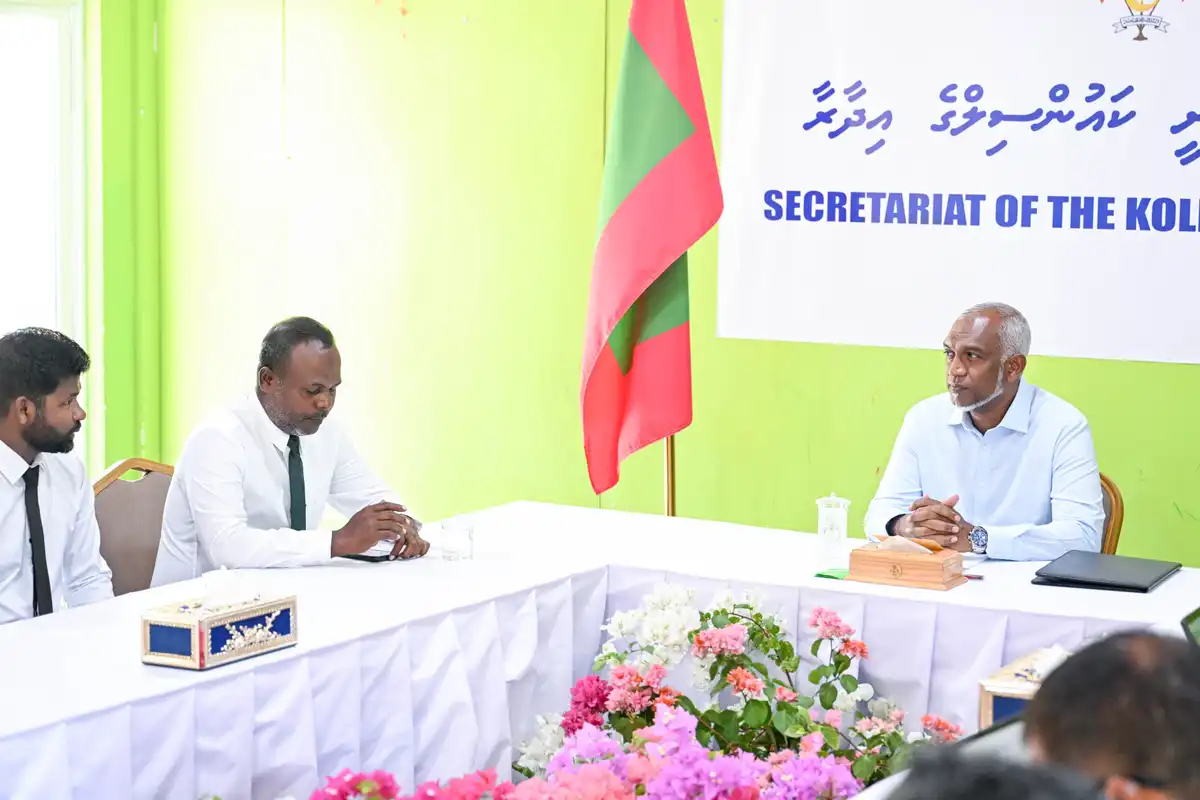
President Dr. Mohamed Muizzu meets with the Vilufushi Island Council. | President's Office
The Auditor General’s Office has stated that the Th. Vilufushi Island Council failed to submit its financial statements within the mandatory deadline, and noted discrepancies between the records maintained by the office and the statements subsequently filed.
The 2024 compliance audit report for the Th. Vilufushi Council, released by the Auditor General’s Office, highlighted that under Section 35(a) of the State Finance Act, the Financial Responsible Officer of every state institution is required to submit an annual report to the Auditor General. This report, which must include financial statements and an overview of the institution's activities, is due within three months of the end of each financial year.
The Audit Office report further stipulated that the report must be prepared in accordance with the framework established by the Ministry of Finance's financial circular for the preparation of financial statements for island, atoll, and city councils.
The Auditor General’s Office stated that the Vilufushi Council failed to prepare its 2024 annual report and financial statements, and neglected to submit them for audit within the legally mandated timeframe. The office further noted that although financial statements were eventually shared with auditors during the field stage of the audit, significant discrepancies were identified. Specifically, the figures for income and expenditure reported in the council’s "Statement of Comparison of Budget and Actual Amounts" did not align with the records maintained in the Viya module.
The office noted that discrepancies were identified amounting to MVR 811,302 in total revenue received and MVR 2,402 in total expenditures incurred.
Recommending measures to rectify the issue, the office advised that financial statements must be prepared in accordance with the framework established by the Ministry of Finance's circular. These statements must include all information mandated by the State Finance Act and be submitted to the office within three months of the end of each calendar year.
Furthermore, the office has instructed the council to ensure that all financial transactions and related information are regularly updated in the "Viya Module," as mandated by the Local Government Authority (LGA) for managing the finances of local councils. The council is also required to prepare financial statements based on these records and verify, prior to submission, that the statements accurately and honestly reflect the total revenue received, expenditures incurred, and the remaining balance at the end of the financial year.